Approach finance
from a position of strength.
The point before finance is where you still have options.
Whether you are buying, refinancing, expanding or dealing with a declined application, we start with what you want to achieve, show you where you stand and prepare your case before any lender sees it.
Personal · Business · Property · Agricultural Finance.
WHY LOOKINGFOR.FINANCE?
Lenders assess applications. We help you prepare yours, with lending experience on your side and your objectives, not a lender’s products, at the centre. The finance you choose today affects the wealth you build, protect or recover.
Banking experience, on your side
Our advisory panel includes former senior bankers. We know how lenders read an application, and we use that to strengthen yours.
Your case, properly prepared
We start with what you want to achieve and your full situation, then shape the requirement and gather what a lender will need before anyone applies.
The right lender for your situation
Lenders differ in what they will finance. We identify banks and specialist providers whose criteria fit your circumstances.
Your decision, every step
We’re not tied to one lender’s products. You see the options and decide whether to proceed. Nothing goes to a lender without your agreement.
WHAT ARE YOU LOOKING TO FINANCE?
Choose the area that best matches what you are looking to finance, then explore the options available.
Business Finance
Cash-flow problems and growth problems look the same on a bank statement, but they don’t need the same funding. We work out what’s actually needed and get the case in order before any lender sees it. That covers working capital, bridging, trade finance, vehicles and equipment.
Bridging Finance
The money is coming — a property sale, a settled transaction, a confirmed payment — but it isn’t there yet. Bridging covers the period until it lands.
Vehicle & Asset Finance
The vehicle, machine or equipment the business runs on, whether you’re replacing something worn out or adding capacity. Paid off over time rather than out of cash reserves.
Trade Finance
You’ve won the order, but stock has to be paid for before the customer pays you. Trade finance covers the stretch in between.
Working Capital
Salaries, suppliers and rent don’t wait for your debtors. Working capital keeps the month running when money in and money out don’t line up.
Commercial Property Finance
You might be weighing up a building, refinancing one you own, or putting a development together. We work out what the transaction actually needs and get the case in order before any lender sees it. That covers buying, refinancing, releasing cash from property you already hold, and development funding.
Property Acquisition & Refinance
Buying a building, refinancing the one you’re in, or taking cash out of property you already own — whether you occupy it or let it to tenants.
Property Development
From land through to completion — offices, industrial, retail or residential units. Structured around what it costs to build and how the project pays it back.
Bridging Finance
The money is coming — a property sale, a transfer sitting at the Deeds Office — but it isn’t there yet. Bridging covers the period until it lands.
Agricultural Finance
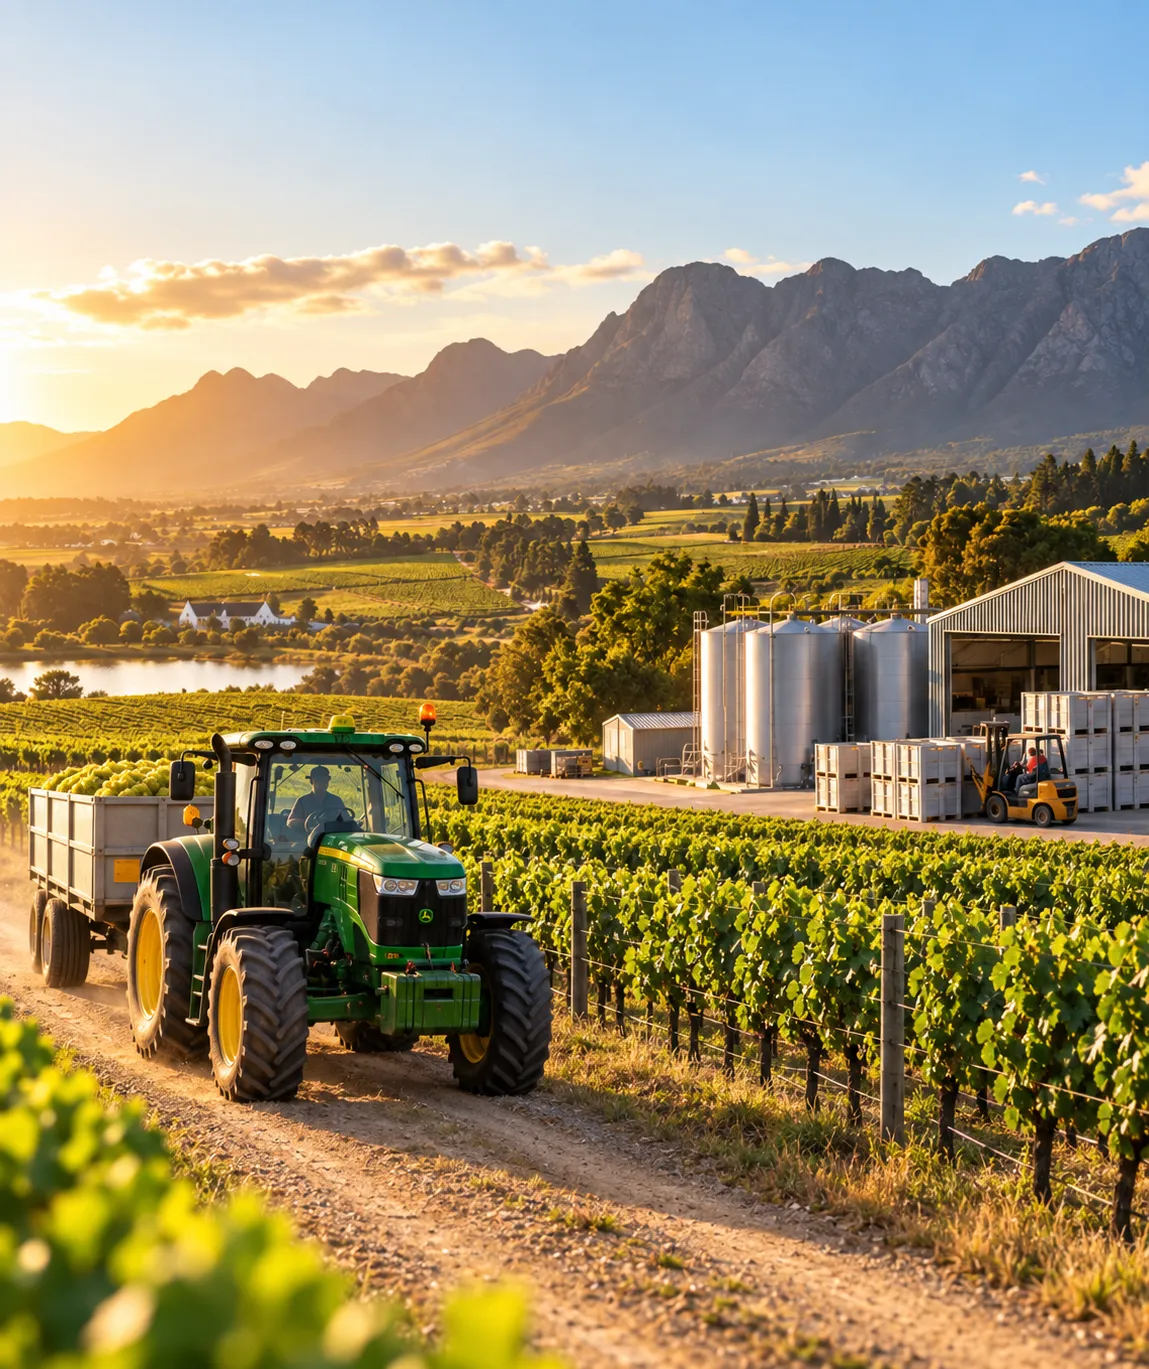
You might be buying land, putting up infrastructure, replacing a machine, or needing cash to carry you through to harvest. We work out what the operation actually needs and get the case in order before any lender sees it. That covers farm property, development and improvements, equipment, working capital and refinancing.
Farm Property Finance
Buying a farm, refinancing one you own, or raising cash against land you already hold — whole farms, estates or additional land.
Agricultural Development & Improvements
Irrigation, sheds, packhouses, fencing, water infrastructure, new plantings. The work that lifts what the farm can produce, paid for over time rather than out of one season’s income.
Equipment Financing
Tractors, implements, harvesters, bakkies — the machinery the season depends on. Funded over its working life instead of tying up cash at the start.
Personal Finance
The decisions here are the big ones — a home, a car, the gap between selling and transferring. We help you understand what you’re actually committing to and get the case in order before any lender sees it. That covers home loans, bridging and vehicle finance.
Bridging Finance
You’ve sold, but transfer takes months and you need some of that money now. Bridging releases part of the proceeds before registration goes through.
Home Loans
Buying, building or refinancing a home. What you can comfortably carry, what you’ll need up front, and how the bank will read your application — before you submit it.
Motor Vehicle Finance
Buying or refinancing a car. What it really costs each month, what the deposit and balloon do to that number, and whether the deal in front of you is the one to take.
FINANCIAL TOOLS & CALCULATORS
Understand the numbers before you apply.
Use our practical calculators and assessment tools to explore repayments, compare finance options, understand your property position and identify what may need attention before formal application.
Finance planning & decision
Understand the cost, compare your options and assess how prepared your finance requirement is.
Repayment & Rate Sensitivity
Estimate your monthly repayment, total interest and how changes in interest rates could affect the cost of your finance.
Finance Offer Comparison
Compare finance offers across rate, repayment, term, fees and balloon to see what is really driving the overall cost.
Finance Readiness Assessment
Find out how a lender will read your application, and what to fix before you submit it.
Property finance tools
Explore affordability, purchase costs, property value, equity and refinancing before committing to the next step.
Property Affordability
Estimate the finance amount and property price your income, expenses, debt and available deposit may potentially support.
Purchase Cash & Shortfall
Estimate the cash you may need for a property purchase, including your contribution, transfer duty, transaction costs and any potential shortfall.
Loan-to-Value (LTV)
How much of a property’s value a lender will fund, and what that leaves you to put in. Work it from the price, the finance amount, or the LTV you’re aiming for.
Property Equity & Equity Release
Estimate your property equity, current LTV and how much additional finance the property may potentially support.
Refinance & Break-Even
Compare your current finance with a proposed refinance and see whether the repayment saving justifies the costs and change in term.
START THE CONVERSATION
It doesn’t need to be worked out yet. That’s usually the point at which it’s worth talking.
We’ll call to understand the situation, tell you what we see, and agree the next step with you. If any fees apply, you’ll know before anything proceeds.
No application. No credit check. Nothing goes to a lender without your agreement.
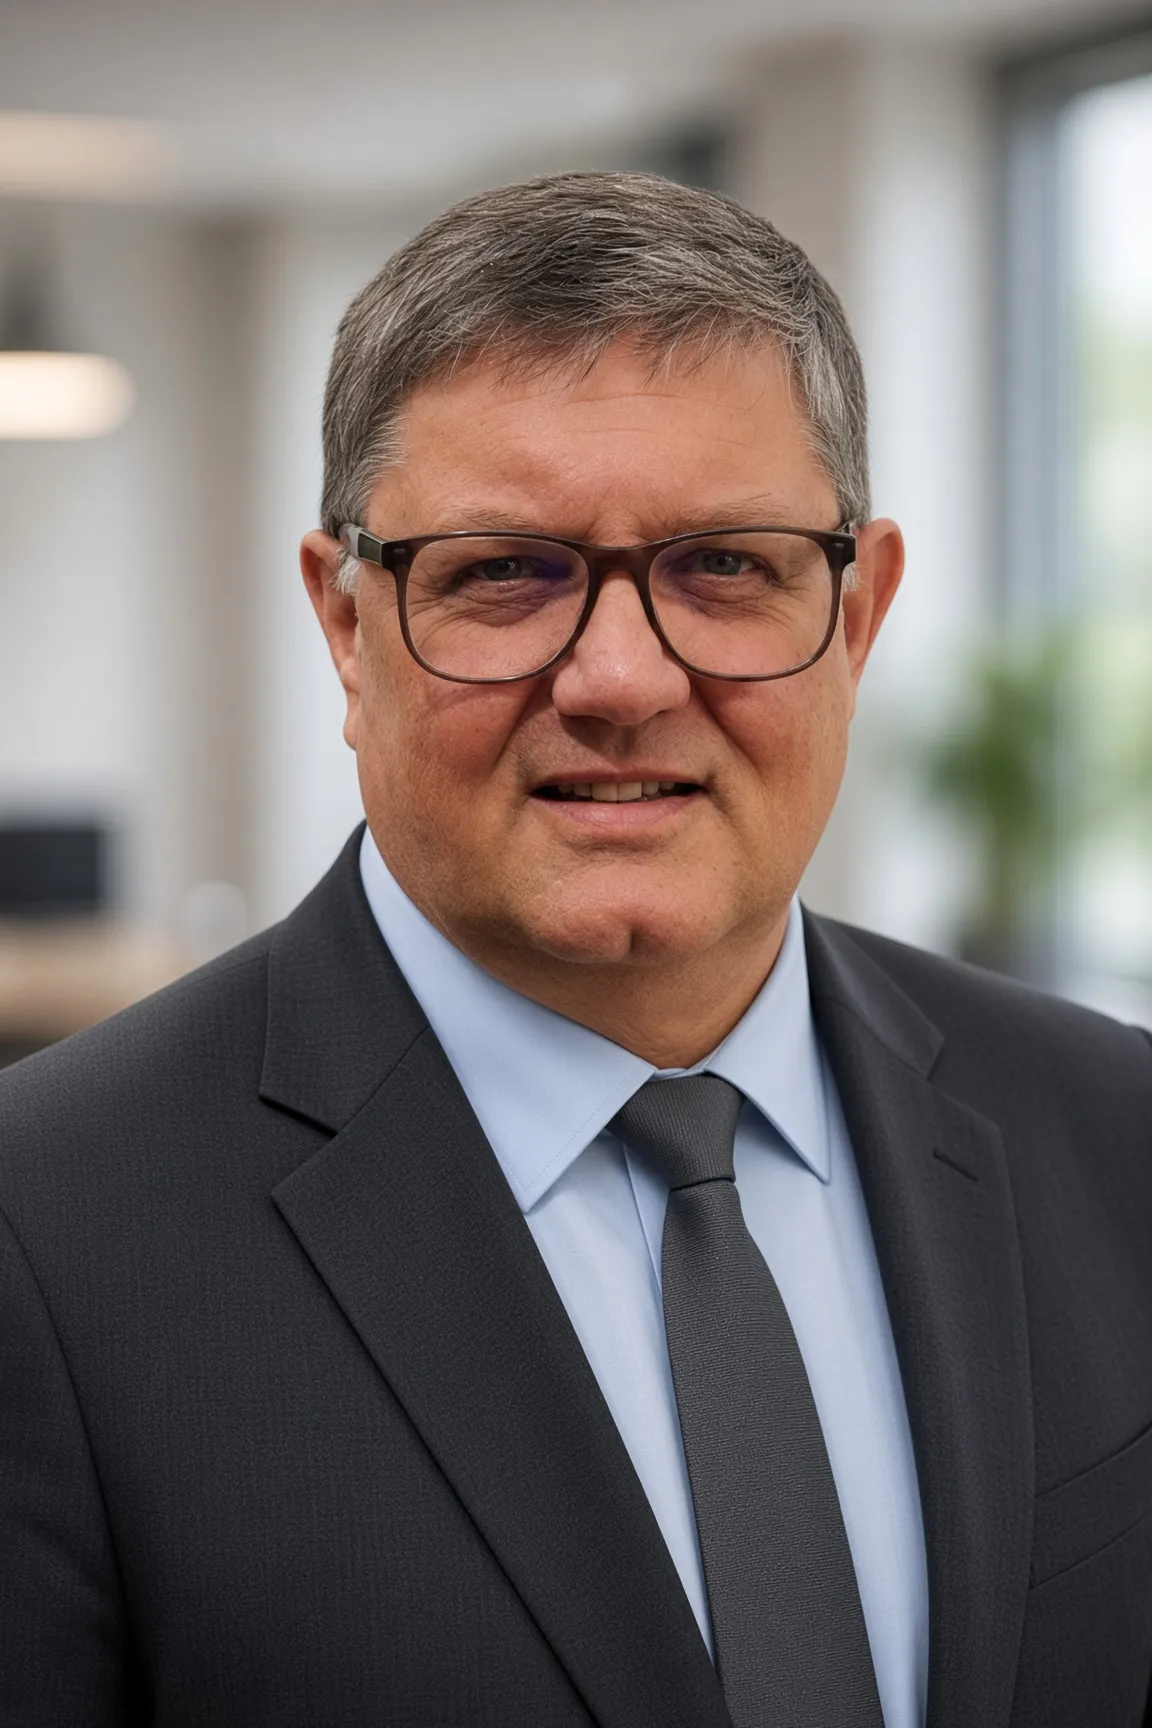
Joe Meyer
060 586 7783
You’ll speak to Joe directly, not a call centre.
email:
WhatsApp:
060 016 5253
email: [email protected]
WhatsApp: 060 016 5253
Tell us what you are planning.
Tell us roughly what you’re working on. We'll call to talk it through — no application and no credit check at this stage.
LookingFor.Finance is not a lender. Each lender makes its own decision, and approval is never guaranteed. This content is general information, not financial, tax or legal advice, and does not take your personal circumstances into account. LookingFor.Finance assesses, structures and positions your finance requirement. Qualifying applications are referred to suitable regulated financial services providers via at360 Finance Stellenbosch.
© 2026 LookingFor.Finance. All rights reserved.
